

Latika Tanwar explains how NBFCs can combine responsible underwriting, technology and governance to scale sustainable financial inclusion in India.
By Latika Tanwar
India’s next phase of growth rests on a clear test: whether the millions of MSMEs, rural entrepreneurs, women-led businesses and first-time borrowers still outside the formal credit system can be brought into it on commercially sustainable terms. The demand for credit among these segments is well established. What has taken longer to build is a lending model capable of serving them profitably, at scale, over time. This is the space NBFCs occupy, and how they respond will shape the character of India’s growth over the coming decade.
The scale of the opportunity is well documented. The Reserve Bank of India’s Financial Inclusion Index rose to 70.0 in FY26, up from 67.0 a year earlier, a 4.48% increase driven mainly by higher usage of formal financial services rather than mere access to them. India’s underserved population is not simply being handed bank accounts; it is transacting, saving and borrowing through the formal system with growing regularity. The government has described this as India’s transition towards a high-growth, resilient economy, an ambition NBFCs can advance most directly in the semi-urban and rural markets where unmet credit demand remains largest.
As lending expands into underserved markets, credit assessment increasingly relies on a broader set of indicators beyond traditional documentation. NBFCs have built entire business models around serving exactly this segment. Reaching these borrowers, however, is the more straightforward half of the task. The consequential test is whether that lending can be sustained profitably, cycle after cycle, without compromising portfolio quality or the inclusion mandate that justified the expansion.
Financial Inclusion Beyond Credit Access
Genuine inclusion is measured by progression, not disbursement. A first-time borrower who takes a working capital loan, repays it on schedule, and qualifies for a larger loan on better terms a year later has been included in the way that matters. A borrower pushed into a loan beyond their repayment capacity, who defaults and exits the formal system, has not. That difference comes down to how the loan was structured. Tenures, repayment schedules and collateral norms must reflect how a small trader or first-generation entrepreneur actually earns and spends, in cash-flow patterns that rarely resemble a salaried, urban borrower’s monthly cycle. Pricing must be transparent enough that a borrower knows exactly what is owed and why, so credit strengthens the business rather than over-leveraging it.
This caution is not theoretical. The RBI’s own Financial Stability Report of June 2026 flagged early signs of stress in the micro-enterprise segment, even as overall retail asset quality held up well. A comparable pattern played out earlier in India’s microfinance sector, where borrower over-leveraging led to rising defaults and a contraction in credit supply, a cycle the sector is only now recovering from. Inclusion pursued without underwriting discipline produces the opposite of what it set out to achieve: borrowers pushed further from the formal system, not closer to it.
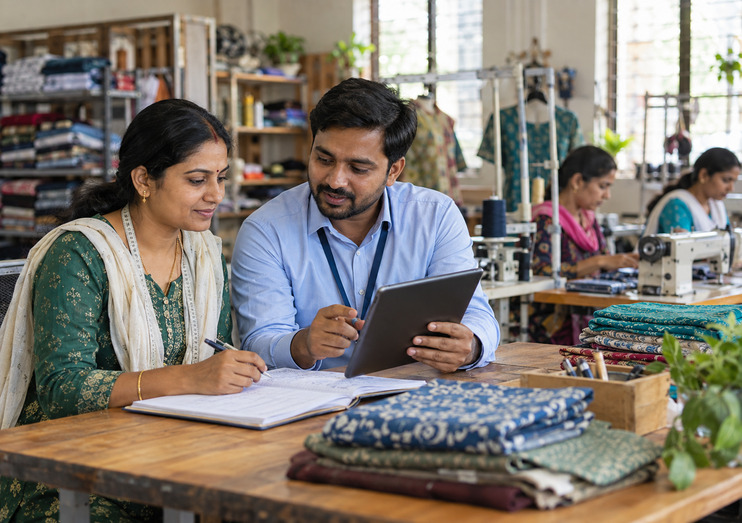
NBFCs can expand access to credit for MSMEs, women entrepreneurs and first-time borrowers only when inclusive lending is supported by disciplined underwriting, transparent pricing, digital tools and strong governance.
Building Commercially Sustainable Lending Models
Sustainability in lending is not a constraint on inclusion; it is what makes inclusion durable. An NBFC that grows its book rapidly without strengthening its risk architecture will not be around long enough to serve its next generation of customers. The fundamentals demand constant recommitment: underwriting that assesses genuine repayment capacity beyond formal income proof, portfolios that avoid concentration in any single sector or geography, and collections practices that are firm without tipping into coercion.
Governance sits underneath all of this. Boards that maintain a clear risk appetite, an independent credit assessment function and regular stress testing are better placed to absorb shocks, whether from a commodity price spike or a broader slowdown. The RBI’ June 2026 Financial Stability Report found that microfinance credit grew for the first time in seven quarters, with borrower over-leveraging easing as the share of borrowers linked to three or more lenders fell to 9.7%, indicating the guardrails adopted across the sector.
Technology as an Enabler of Scalable Inclusion
Digital infrastructure has changed what is operationally possible for lenders serving underserved segments. Nearly 55.49 crore users had been onboarded onto UPI as of June 2026, with transaction volume and value both hitting record levels during the year. Every such transaction leaves a data trail, and that trail increasingly makes a borrower visible to a lender who might otherwise have no documentation to work with.
Digital onboarding has cut the time and cost of acquiring a customer in remote geographies. Alternative credit assessment, drawing on bank statements, GST filings and transaction history, helps lenders underwrite borrowers with no prior credit record but a demonstrable economic footprint. According to data from SIDBI’s MSME Pulse, compiled with TransUnion CIBIL, the number of credit-active MSME entities increased by 65% over the five years to FY25, with new-to-credit entities accounting for 55% of originations in the sub-₹1 crore exposure segment. AI-assisted analytics layered on this data improves approval speed and portfolio monitoring, catching stress before it turns into losses. None of this replaces field judgment. It sharpens it.
NBFCs as Catalysts for Inclusive Economic Growth
The multiplier effect of NBFC lending plays out quietly, in small towns and semi-urban markets rather than in headline transactions. A working capital loan to a manufacturing MSME in a Tier III town supports the wages of its workers and the local suppliers it buys from. Credit to women entrepreneurs is one of the more striking shifts in India’s lending landscape: women’s business-purpose loan portfolios grew 7.5 times between 2017 and 2025, expanding at a 31% compound annual growth rate over the last three years, well ahead of overall commercial credit growth of 17%, as per the NITI Aayog research. Financing a transport operator or a small contractor keeps entrepreneurial activity alive in markets larger, centrally underwritten lenders often overlook. NBFCs are not merely filling a credit gap here; they are participating in regional economic development, enterprise by enterprise.
The Road Ahead
The next phase of credit expansion in India will not be built by NBFCs alone. Policymakers have a role in shaping data-sharing and account aggregator infrastructure that makes alternative credit assessment more reliable industry-wide. Technology providers have a role in making underwriting tools accessible to mid-sized and smaller NBFCs, not only the largest players. NBFCs carry the responsibility of strengthening governance even as they scale, resisting the pull to chase growth at the expense of portfolio discipline.
Key Takeaway
The NBFCs that shape India’s lending landscape over the coming decade will be the ones that refuse to treat financial inclusion and commercial sustainability as separate objectives. Built together, they create durable value: for the customer who gains genuine access to credit, for the investor who backs a resilient balance sheet, and for an economy that grows stronger precisely because its growth reaches further.
About the Author: Latika Tanwar, Director and Co-promoter, Namdev Finvest Limited
© Copyright Disclaimer: All rights reserved. No part of this report may be reproduced, republished, distributed or transmitted in any form without prior written permission from India CSR®